Has the Housing Market
Fallen Apart Yet
By Matt Dutton, Certified General Real Estate Appraiser
Bracing for a Housing Market Crash
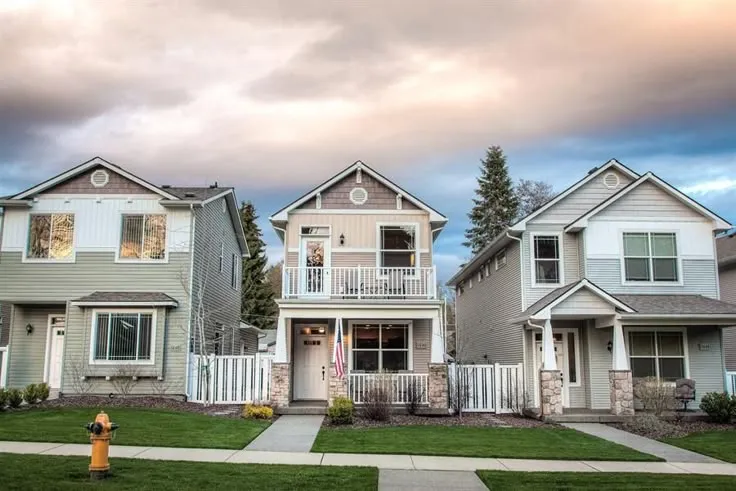
Questions like these have become more common recently. Potential buyers and sellers appear to be bracing themselves for a crash. Rapidly rising interest rates have quickly cooled the red-hot housing market by significantly diminishing buying power. Stories of recent buyers, particularly those with lower down payments, already under water on their homes have begun to surface.
Local Realtors Expect a “Softer Landing”
It appears that this is certainly the case in some more major metropolitan areas around the country. However, several local realtors have recently told our appraisers that they are anticipating a "softer landing." As real estate appraisers, the appraisers at Spurgeon Appraisals strive to frequently engage with local real estate agents, builders, loan officers and other knowledgeable sources to better understand the ever-changing nature of the market. Frequent conversations with real estate agents become even more necessary when sales activity is limited.
How We Read the Market
Talking to the Market
Frequent conversations matter even more when sales activity is limited.
Local real estate agents
Builders
Loan officers
Other knowledgeable sources
Spurgeon Appraisals
A better understanding of a changing market
Farm · Commercial · Home appraisals | Missouri · Illinois · Iowa
Low Housing Inventory in Rural Areas
As demand still outpaces supply in a significant way in more rural areas, the primary difficulty for many agents remains finding inventory to sell. Forbes.com recently noted, "Low housing inventory has been a challenge since the 2008 housing crash when the construction of new homes plummeted. It hasn’t fully recovered—and won’t in 2023."
Why This Isn’t 2008
Bankrate.com recently noted that "The typical homeowner with a mortgage has stellar credit, a ton of equity and a fixed-rate mortgage locked in at a rate well below 5 percent. So no foreclosure crisis looms." This stands in stark contrast to the Great Recession in 2008 and also hints at a less severe housing market reaction.
Then and Now
2008 vs 2023
Why this looks less like the Great Recession.
The Great Recession
2008 Housing Crash
- A foreclosure crisis
- Construction of new homes plummeted
Early 2023
No Foreclosure Crisis Looms
The typical homeowner with a mortgage has:
- Stellar credit
- A ton of equity
- Fixed‑rate mortgages locked in well below 5 percent
Quotes: Bankrate.com and Forbes.com, as cited in the article
Farm · Commercial · Home appraisals | Missouri · Illinois · Iowa
Home Sales Are Slowing, but Prices Are Holding
According to Forbes.com, existing home sales have been steadily declining each month for the last year or so. Locally, activity has also slowed. Whether this is due to changing seasons or rising interest rates could be debated. However, we have not yet seen a concurrent statistically significant decline in prices.
“It seems we have already reached the bottom of the low home sales activity,” Nadia Evangelou, senior economist and director of forecasting for the NAR, told Forbes.com. “And with mortgage rates stabilizing near 6%, we expect the housing market to turn around in 2023 … and rebound in 2024.”
Our Local Market
Why a Softer Landing?
Several local realtors have told our appraisers they expect a softer landing.
Demand Outpaces Supply
In more rural areas, the main difficulty for agents is finding inventory to sell.
Low Inventory Since 2008
New home construction plummeted after the 2008 crash and hasn’t fully recovered.
Strong Homeowners
The typical homeowner with a mortgage has stellar credit, a ton of equity and a fixed rate well below 5 percent.
Prices Holding
Sales activity has slowed, but there’s no statistically significant decline in prices yet.
Farm · Commercial · Home appraisals | Missouri · Illinois · Iowa
Regardless of what happens in the broader market, we will continue to provide reliable appraisals for all purposes. Be sure to contact us today if you are in need of expert opinions of value.